India Must Attach Reciprocal Conditions to Nuclear Finance


Opening a new source of capital requires a clearer account of construction risk and public responsibility. Without reciprocal mechanisms, nuclear finance becomes a risky investment.
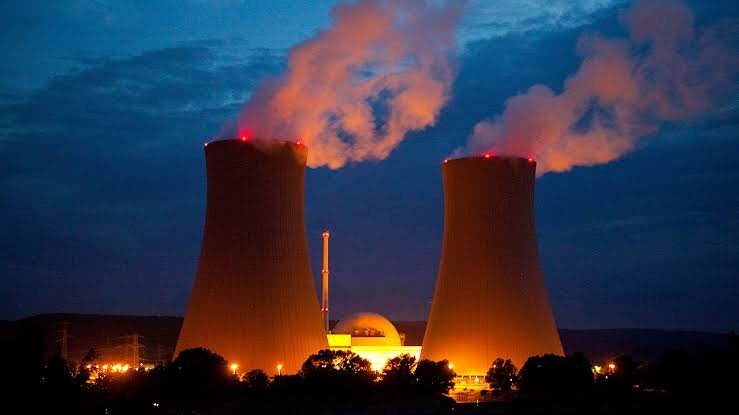
India’s nuclear expansion has reached a practical financing dispute. On September 2, NITI Aayog member Abhay Karandikar called for a review of rules that exclude nuclear investments from important green-finance channels. Industry participants want access to green bonds, green loans and blended finance. With India targeting 100 gigawatts of nuclear capacity by 2047, their request deserves attention. The terms on which that money becomes available deserve equal scrutiny.
India should allow qualifying nuclear projects to access green finance. But eligibility should depend on independently assessed environmental safeguards and transparent financing arrangements. A project’s low emissions can justify considering it for climate finance; they cannot establish whether it will be completed on time, repay its lenders or leave future costs to the public. The government should resolve these questions together as it opens the sector to greater private participation.
The energy case is substantial. The International Energy Agency forecasts that India’s electricity demand will grow by an average of 6.4% annually between 2026 and 2030. Coal will supply around 70% of generation in 2025. Nuclear power offers a source of low-carbon electricity available through the night and during weak wind output. It can complement renewable generation, storage and transmission, provided projects can be delivered at a cost and on a timetable that justify their contribution.
That explains the pressure for change. NITI Aayog’s February 2026 report on the power sector proposed making nuclear eligible for green bonds because of its low-carbon credentials. The September industry request puts implementation at issue. Sovereign bonds finance government expenditure, while green deposits support lending by financial institutions. These channels require separate rule changes. Inclusion would widen access to designated pools of capital; it would not guarantee that investors will fund every reactor proposed.
India’s own financing experience should temper expectations. The Economic Survey 2025–26 describes the yield advantage of its sovereign green bonds over comparable conventional bonds as intermittent, ranging from zero to six basis points, at most 0.06 percentage points. This is evidence about government borrowing, not a forecast for nuclear loans. It nevertheless cautions against assuming that a green label delivers a large, dependable financing discount. Access to more investors and a lower borrowing cost are related possibilities, not interchangeable outcomes.
International nuclear financing reveals a further distinction. In its 2025 assessment, the IEA reported that nuclear green bonds had raised more than $5 billion, mainly for extending reactor lifetimes and refinancing projects entering operation. That record demonstrates a useful financing channel. It provides much less evidence about investors’ willingness to absorb the risks of building a new reactor. An operating plant with electricity sales presents a different proposition from an unfinished project with an uncertain completion date.
Those differences matter because delays postpone revenue while financing costs accumulate. The IEA identifies construction risk and predictable cash flows as central to attracting lenders. Long-term electricity purchase contracts and government guarantees can help. If their terms pass overruns into electricity bills or require taxpayers to cover losses, those commitments should be disclosed before approval. Public support can be justified by the value of reliable low-carbon power. Its cost and the obligations retained by private investors must be visible.
Environmental eligibility requires equally careful treatment. Nuclear’s climate contribution does not erase accident risks or radioactive-waste obligations. Fukushima’s consequences extended beyond radiation exposure: the World Health Organization documented disrupted healthcare, psychological harm and increased mortality among elderly evacuees in temporary accommodation. A financing framework that considers emissions while leaving emergency capacity and long-term waste management underfunded would give an incomplete account of environmental responsibility.
Asia already has a relevant policy precedent. In November 2025, the Asian Development Bank changed its energy policy to permit support for nuclear power, including investment, subject to rigorous assessment and safety, environmental and social safeguards. It subsequently agreed to cooperate with the International Atomic Energy Agency. That decision establishes a route for considering projects without promising that each will receive funding. India can apply the same principle when revising its domestic financing rules.
For Indian projects, green eligibility should require independently reviewed emissions estimates, site-specific environmental assessment and funded arrangements for waste management and decommissioning. Projects must also satisfy the nuclear regulator’s safety requirements. Financial institutions should publish how proceeds are allocated and how compliance is verified, with procedures for correcting failures. These conditions would allow investors to assess the environmental claim without mistaking it for a guarantee of safety or repayment.
Public financial support needs an additional test. Before offering guarantees or subsidised capital, the government should publish expected construction costs, contingency allowances and the division of responsibility for overruns. Assessments should compare the project with credible alternatives for delivering the same electricity service. Experimental reactor designs need explicit research funding and demonstration milestones; projected savings should not be presented as established commercial performance. This would preserve room for innovation while making its risks visible.
A workable reform would distinguish environmental eligibility, commercial financing and public subsidy, with evidence required for each decision. That distinction matters across Asia as governments seek reliable electricity and development banks reconsider nuclear investment. India can make a useful contribution by showing how private capital and public accountability can develop together. Its nuclear sector should gain access to green finance on terms that explain what is being funded, what it can deliver and who pays if it falls short.
Continue reading
The Geoeconomics of India–EU Defence Cooperation
India and the EU seek to move beyond defence procurement towards technology-sharing, joint manufacturing and resilient supply chains. The challenge lies in…

BRICS Needs More Women in Power to Unlock Growth
BRICS wants more power in the world economy. It should begin by giving women more power over economic decisions. The World Bank…

India’s Next Digital Export Should Be Sovereignty
India has spent the last ten years asking itself if technology can assist its population of 1.4 billion in overcoming the natural…
Dr. Simran Keshwani
Dr. Simran Keshwani is Founder and Research Lead at IndiaForth, a Sydney-based geoeconomic intelligence firm focused on India’s rise and emerging opportunities for governments, businesses and institutions. A political economist, her research focuses on industrial strategy, energy transitions, economic security and India’s international partnerships.
Janvi Singhi
Janvi Singhi is a Senior Research Fellow at IndiaForth and Research Associate at Asia-Pacific Bureau of Organization for Threat Assessment and Peacebuilding (OTAP). She holds a Master’s degree in Political Science and is a Gold Medalist in International Relations. Her research focuses on geopolitics, geoeconomics, strategic affairs, India’s foreign policy, and specialising in Indo-Pacific and Indo-China relations.